
Ontario’s October Housing Market: Prices, Sales & Supply
October 1, 2026
Introduction
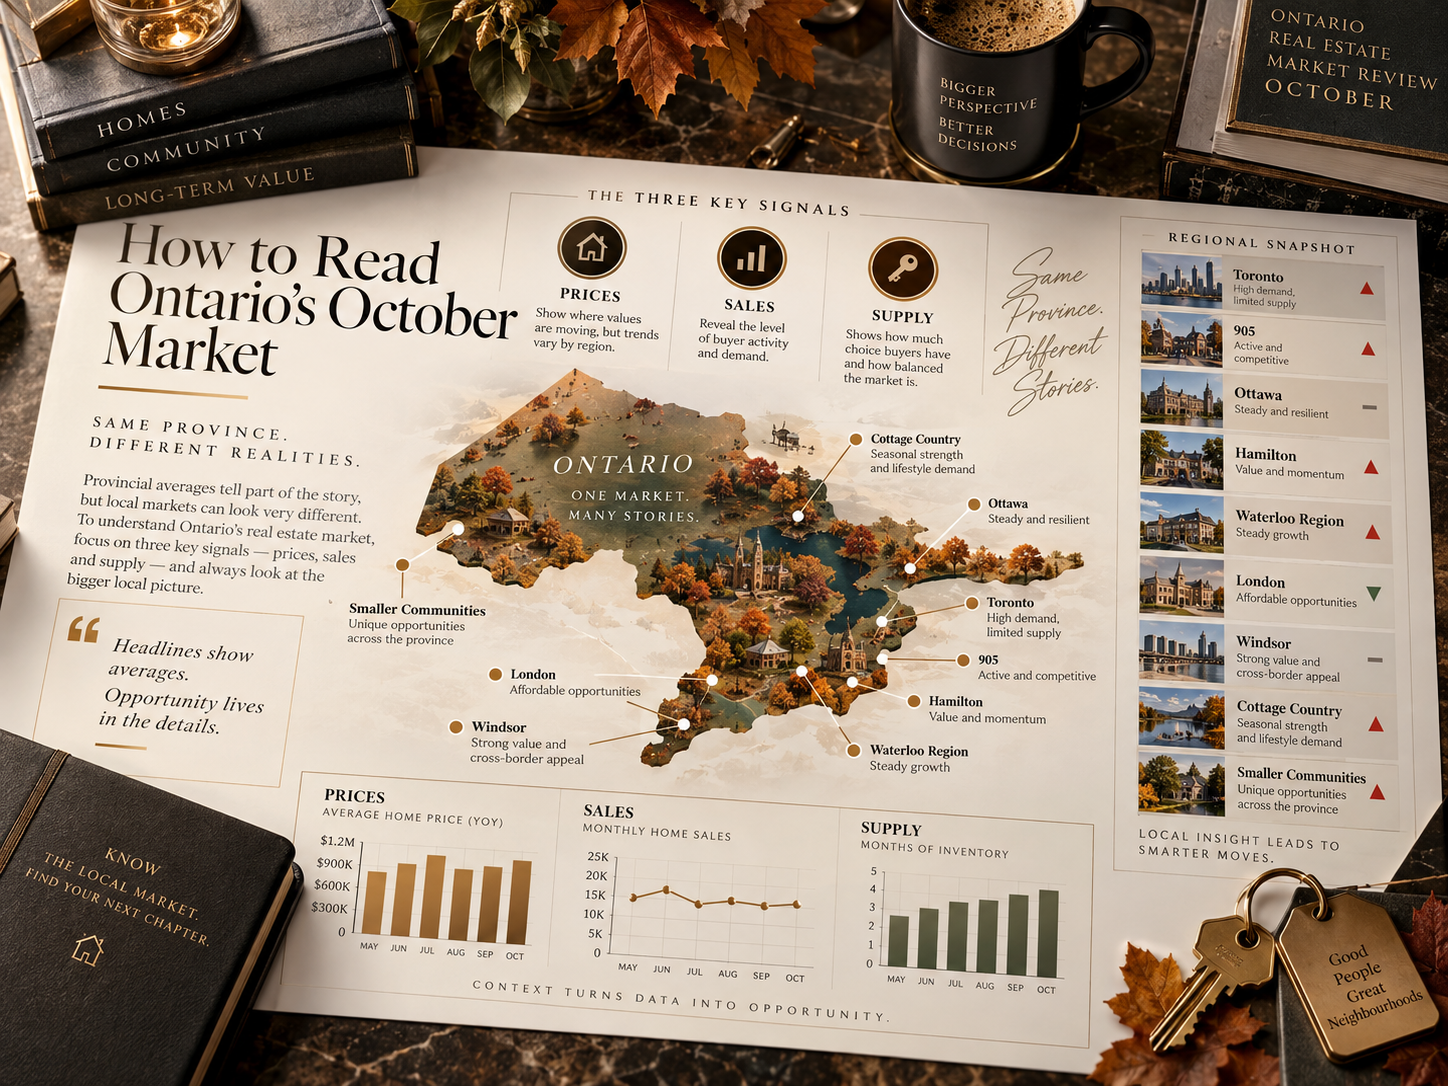
October is one of the most closely watched months in Ontario real estate. The market is back in motion after summer, buyers who paused during the vacation season are active again, and sellers often hope to complete a move before the holidays. That makes October data useful—but only when it is read in context. Ontario does not have one single housing market: conditions can differ sharply between Toronto, the 905, Ottawa, Hamilton, Waterloo Region, London, Windsor, cottage country and smaller communities.
This October market review explains the three signals that matter most: prices, sales and supply. It also outlines what changed to look for in the latest local real estate board releases and why a headline about “the Ontario market” rarely tells the whole story. Because board statistics are released on different schedules and use local boundaries, the most reliable conclusion comes from comparing the same market, property type and time period—not from relying on one provincial average.
1. Start With the Right October Market Snapshot
A meaningful October snapshot should compare the latest month with both the previous month and October of the prior year. Month-over-month results show the immediate direction of the market, while year-over-year results reduce the risk of mistaking normal fall seasonality for a major shift. For example, a decline in new listings from September to October may be entirely typical; whether active inventory is still rising compared with last October is often the more useful question.
- Average and median sale price: useful measures of value, but sensitive to the mix of homes that sold.
- Sales: the number of completed transactions, a direct signal of buyer activity.
- New listings: properties brought to market during the month.
- Active listings: homes available for purchase at month-end, the clearest view of buyer choice.
- Sales-to-new-listings ratio and months of inventory: measures that help identify whether negotiating power is leaning toward sellers, buyers or neither.
The distinction between new and active listings is especially important. A market can receive fewer new listings in October yet still offer buyers more choice if homes are taking longer to sell and unsold inventory is accumulating. Conversely, a busy sales month can quickly absorb fresh supply, leaving competition intense even if listing counts look healthy at first glance.
2. Read Home Prices Beyond the Headline Average
Price headlines can be compelling, but they are not always a clean measure of what happened to the value of a typical home. The average sale price rises when a larger share of higher-priced detached homes changes hands and falls when more condos or entry-level properties sell. That compositional effect can be substantial in a diverse province such as Ontario.
For a clearer price read, examine median prices, benchmark or home price index measures where a local board publishes them, and segment-level results. Detached, semi-detached, townhouse and condominium markets respond differently to mortgage rates, affordability limits and available supply. A detached-home average may hold firm while condo prices soften, or an affordable suburban segment may see stronger demand than a high-priced urban segment.
“The most useful price comparison is like for like: the same location, the same home type and the same point in the seasonal calendar.
Sellers should also watch the sale-to-list-price ratio and days on market. A stable average price paired with a falling sale-to-list ratio may indicate that buyers are negotiating more successfully. Buyers should not assume a lower average means every listing is discounted: well-priced homes in scarce neighbourhoods can still attract competing offers, particularly when they are turnkey, close to transit or located in sought-after school catchments.
3. Sales Show Demand—But Financing Shapes the Pace
Sales activity reveals how many households were able and willing to complete a purchase. In October, demand is shaped by employment confidence, household formation, rental-market pressure, local migration and, most immediately, borrowing costs. Changes in mortgage qualification, fixed-rate offers and expectations for future interest rates can affect buyer behaviour before they visibly change prices.
A rise in sales is generally encouraging, but it should be interpreted alongside listing activity. If sales increase faster than new listings, competition may tighten. If sales rise while active listings rise even faster, buyers may still have ample choice and more time for due diligence. Likewise, a slower sales month does not automatically mean weak demand; buyers may be waiting for more supply, a rate decision or clarity on their financing.
Look for the share of listings that sell, the number of conditional versus firm transactions where available, and the gap between asking and sold prices. These details help distinguish a market where buyers are simply taking longer to decide from one where sellers need to adjust expectations. They also reinforce the value of mortgage pre-approval, realistic pricing and careful review of comparable recent sales.
4. Supply Is the Key to Bargaining Power
Supply is often the best explanation for why two Ontario markets can move in opposite directions. Active listings measure the choice available today, while months of inventory estimates how long it would take to sell current inventory at the latest sales pace. Lower months of inventory usually points to a tighter market; higher months of inventory gives buyers more alternatives. Neither measure should be treated as a universal cut-off, because normal inventory levels vary by location and property type.
October can produce a useful supply test. Some owners list in early fall to capture active buyers, while others delay until spring. If inventory builds through the month, buyers may gain leverage on properties that are overpriced, need work or have been listed for several weeks. If supply is absorbed quickly, sellers with well-prepared homes may retain an advantage. The crucial question is not simply whether listings are up or down, but whether they are moving faster or slower than demand.
- For buyers: compare similar active listings with recent sold properties before making an offer.
- For sellers: price against current competition, not against a neighbour’s peak-period sale.
- For investors: assess vacancy trends, carrying costs and condominium fees alongside resale inventory.
- For everyone: separate province-wide commentary from the evidence in the specific neighbourhood being considered.
5. Ontario Is a Collection of Local Markets
Toronto and the surrounding 905 communities are often influential in provincial coverage because of their transaction volume, but they should not stand in for all of Ontario. Ottawa can be shaped by government and technology employment. Waterloo Region responds to its own employment base and new construction pipeline. Hamilton, Niagara and Durham may reflect commuter demand as well as local conditions. Southwestern and northern communities can have different price points, inventory patterns and buyer pools altogether.
The same local approach applies within a city. Condo supply near transit, purpose-built rental availability, new-build completions, zoning changes and the number of detached family homes for sale can create very different conditions only a few kilometres apart. A useful October report therefore breaks results down by municipality, neighbourhood and housing type whenever the data permits.
Conclusion: Turn October Data Into a Better Decision
Ontario’s October market is best understood as a balance between price resilience, completed sales and the supply available to meet demand. Rather than reacting to one average-price headline, compare October with September and with the same month last year; review active listings and months of inventory; then narrow the analysis to the home type and community that matter to you. This approach reveals whether conditions are genuinely tightening, stabilizing or giving buyers more room to negotiate.
For a purchase or sale decision, combine the latest local board statistics with recent comparable sales, a realistic budget and advice tailored to the property. Markets can change quickly, but disciplined interpretation turns monthly data from a headline into a practical plan.
Comment (0)
Leave a comment
Your email address will not be published. Required fields are marked *
© 2026 A1 AI Agents Inc. All rights reserved.
Information presented is believed to be accurate but is not guaranteed and should be independently verified. Data has been obtained in part from the Toronto Regional Real Estate Board (TRREB) and is provided exclusively for consumers with a genuine interest in the purchase, sale, or lease of real estate. Any unauthorized use, reproduction, or distribution of this material, in whole or in part, is strictly prohibited.